Entry in Who Saves With Pay-As-You-Go Insurance
Is Pay-Per-Mile Car Insurance Worth It for Seniors and Retirees?
Learn how pay-per-mile car insurance works for retirees and senior drivers. See how reduced annual miles, base rates, and state rules affect your savings.
By Hana Sato · Writer
Published
Answer in brief
Pay-as-you-go car insurance offers substantial savings for retirees and older drivers who have significantly reduced their driving after leaving the workforce. Because pricing separates a flat monthly base rate from a per-mile charge, seniors driving under 6,000 miles per year often pay less than they would on traditional flat-rate policies. However, comparing base rates, evaluating tracking technology, and factoring in statutory senior discounts are essential steps before making a change.
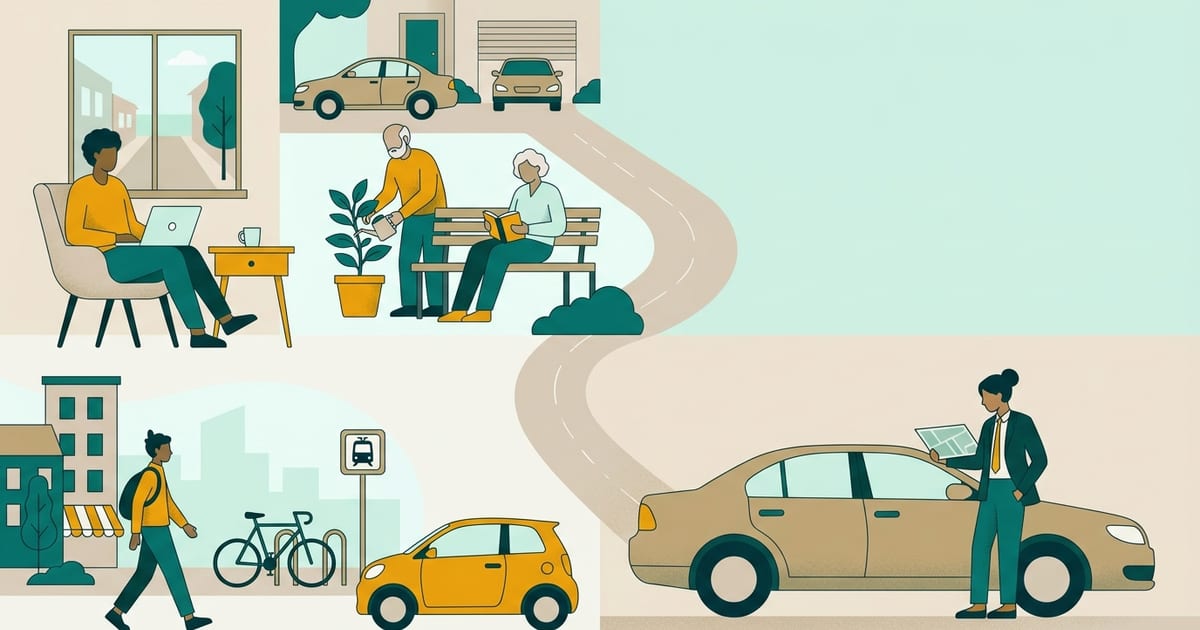
For many households, retirement brings an immediate, fundamental change in daily travel. The daily commute vanishes, errands consolidate into fewer trips, and the family vehicle often sits parked in the driveway for days at a time. Yet many older drivers continue paying the same flat-rate auto insurance premiums they paid during decades of full-time commuting.
According to the National Association of Insurance Commissioners (NAIC), the countrywide average auto insurance expenditure reached $1,281 in 2023, reflecting a 13.98% single-year increase. For retirees living on a fixed income, absorbing regular premium increases for a vehicle driven only a few thousand miles each year makes little financial sense. This has prompted many older motorists to explore pay-as-you-go car insurance and low-mileage policies to align their premiums with their actual road exposure.
Why Retirement Dramatically Lowers Driving Risk
Auto insurance pricing relies on statistical risk pools. Insurers evaluate how often drivers in specific demographic and mileage categories experience collisions and file claims. When motorists retire, their risk profile improves across multiple key dimensions: they avoid rush-hour traffic, log fewer total miles, and travel primarily during safer daylight hours.
Data compiled by the Insurance Information Institute (Triple-I) reveals that drivers aged 65 to 74 have a fatal-crash involvement rate of 15.44 per 100,000 licensed drivers—the lowest rate among all age groups. While involvement climbs slightly to 16.63 per 100,000 for drivers 75 and older, older motorists remain significantly safer on a per-capita basis than drivers in their twenties and thirties. When combined with a dramatic reduction in annual mileage, retirees represent one of the lowest-risk segments on the road.
How Pay-Per-Mile Billing Functions for Retirees
Unlike standard policies that charge a fixed semi-annual premium regardless of whether the car leaves the garage, pay-per-mile insurance separates costs into two transparent components: a monthly base rate and a per-mile rate.
The monthly base rate covers the non-driving risks your car faces even when parked, such as weather damage, vandalism, theft, or falling objects covered under comprehensive coverage. The per-mile rate, typically several cents per mile driven, covers operational road risks like liability and collision. If you take an extended vacation without your car or simply stay home, your bill reflects only the base fee.
| Annual Miles Driven | Typical Traditional Premium | Pay-Per-Mile ($40 Base + $0.06/Mile) | Estimated Difference |
|---|---|---|---|
| 2,500 miles/year | $1,350 | $630 | Save $720 (53%) |
| 5,000 miles/year | $1,350 | $780 | Save $570 (42%) |
| 7,500 miles/year | $1,350 | $930 | Save $420 (31%) |
| 10,000 miles/year | $1,350 | $1,080 | Save $270 (20%) |
State-Specific Rules and Senior Driver Discounts
State insurance laws significantly influence how insurers set rates and calculate mileage discounts. Knowing your state framework helps you confirm that your carrier applies all mandatory credits.
- California (Cal. Ins. Code § 1861.02): Mandates that auto insurance rates must be determined primarily by three factors in decreasing order of importance: driving safety record, annual miles driven, and years of driving experience. Furthermore, qualifying drivers must receive a Good Driver Discount of at least 20% below the rate otherwise charged.
- Florida (Fla. Stat. § 627.0652): Mandates that premium rates for liability, personal injury protection (PIP), and collision coverages must include a discount when the principal operator is 55 or older and successfully completes an approved motor vehicle accident prevention course. The discount remains effective for three years, provided the driver maintains a clean record with no moving violations or at-fault crashes.
- Texas (Texas Department of Insurance guidance): Texas law does not mandate auto insurance discounts for age, course completion, or low mileage. Insurers operating in Texas may offer voluntary discounts, but no statutory rule compels them.
Steps to Evaluate Pay-As-You-Go Insurance in Retirement
Before canceling an existing flat-rate policy, follow these structured steps to ensure a pay-per-mile arrangement will genuinely reduce your annual household expenses without sacrificing essential protections.
- 1
Audit Your Actual Monthly Mileage
Check your odometer at the start and end of a typical month, or review past maintenance receipts that record your odometer readings over the last two years. Many retirees drive far fewer miles than they assume.
- 2
Review Existing Discount Stacking
Examine your current policy declarations page. If you receive large multi-policy bundling discounts or a statutory course discount (such as under Fla. Stat. § 627.0652), compare whether separating your auto insurance produces a lower net household cost.
- 3
Adjust Deductible and Collision Options
According to Triple-I guidance, increasing a collision or comprehensive deductible from $200 to $500 can cut premium costs by 15% to 30%, while moving to a $1,000 deductible can save 40% or more. If you drive an older car worth less than 10 times the annual physical damage premium, consider dropping collision and comprehensive altogether.
- 4
Examine Daily Mileage Caps
If you occasionally take day trips to visit grandchildren or travel cross-country, verify whether the carrier applies daily mileage caps. Most pay-per-mile insurers charge for only the first 150 to 250 miles driven in a single calendar day.
Questions & answers
Can I keep my senior defensive driving discount if I switch to pay-per-mile insurance?
In states where senior defensive driving discounts are mandated by statute—such as Florida under Fla. Stat. § 627.0652—insurers must apply the mandated reduction to your base or per-mile coverage rates for liability, PIP, and collision if you meet the statutory course requirements. In non-mandate states like Texas, discount availability depends on individual insurer filing rules.
What happens if a retiree takes a long cross-country vacation in a pay-per-mile car?
Most pay-per-mile car insurers implement daily mileage caps. Under these caps, you are only charged for a set maximum number of miles (often between 150 and 250 miles) in any single 24-hour period. Any miles driven beyond that cap in the same calendar day are free of per-mile charges.
Does pay-as-you-go insurance monitor my driving speed or sudden braking?
Pure pay-per-mile policies focus primarily on distance rather than behavior, using an OBD-II device or odometer photos to record miles. However, hybrid telematics programs evaluate driving score metrics like sudden braking, acceleration, and late-night driving alongside mileage. Be sure to check whether a policy is distance-only or full behavioral telematics.
Is pay-per-mile insurance available in every state for retirees?
Pay-per-mile availability varies by state regulation. While traditional low-mileage discounts exist nationwide, specialized per-mile programs with tracking devices are approved in select states. Regulators in each state must approve the specific rating plans and tracking technology used.
Terms: Base rate (pay-per-mile), Per-mile rate, Low-mileage discount, Annual mileage, Telematics (usage-based insurance)
Sources and references
Legal figures on this page (minimum limits, filing periods, statutory benefits) are checked against the primary law or the state insurance regulator listed below. Links and figures last verified Nov 2026.
- Insurance Code § 1861.02 — rating factors and Good Driver Discount — California Legislative Information, Cal. Ins. Code § 1861.02Primary lawRates must be determined by, in decreasing order of importance, driving safety record, annual miles driven and years of driving experience; optional factors may follow. Good Driver Discount policies must be at least 20% below the rate otherwise charged.
- Fla. Stat. § 627.0652 — discount for completing an accident prevention course — Florida Senate, Fla. Stat. § 627.0652Primary lawRates for liability, PIP and collision must include a premium reduction when the principal operator is 55 or older and completes an approved course; effective three years; may be conditioned on no at-fault crash or moving violation.
- Companies may offer auto insurance discounts. No law requires discounts. — Texas Department of Insurance (2025)State insurance regulatorNo Texas law or rule mandates auto insurance discounts (for age, low mileage or anything else) or puts a time limit on them; advertising that says otherwise is misleading.
- Background on: Pay-as-you-drive auto insurance (telematics) — Insurance Information InstituteIndependent researchUsage-based and per-mile pricing models, what telematics programmes measure, and state limits on their use.
- Drivers in fatal motor vehicle crashes by age, 2023 — Insurance Information Institute (2025)Statistical dataFatal-crash involvement per 100,000 licensed drivers: 42.40 (16–20), 35.34 (21–24), 28.97 (25–34), 24.18 (35–44), 21.70 (45–54), 19.45 (55–64), 15.44 (65–74), 16.63 (75+).
- 2019–2023 Auto Insurance Database: average premium supplement — National Association of Insurance Commissioners (2025)Statistical dataCountrywide average expenditure $1,281 in 2023 (+13.98%); combined average premium $1,438; state tables for liability, collision and comprehensive.
- What determines the price of an auto insurance policy? — Insurance Information InstituteConsumer guidanceRating factors: driving record, mileage, location, age, gender, vehicle, credit-based insurance score, coverage choices. Notes ZIP-code rating is prohibited in California and Michigan and gender rating is prohibited in seven states.
- Nine ways to lower your auto insurance costs — Insurance Information InstituteConsumer guidanceShop at least three quotes; raising a deductible from $200 to $500 can cut collision/comprehensive cost 15–30%, $1,000 can save 40%+; drop physical damage on cars worth under 10× the premium; bundling, low-mileage and good-student discounts.
Practical guidance on this page is original editorial work. Cited sources support factual statements and do not endorse this site. Dollar ranges described as typical or illustrative are editorial estimates, not figures from these sources.