Guide
How to Compare Pay-As-You-Go Insurance Quotes
A method for comparing pay-per-mile, telematics and conventional quotes on equal terms: realistic mileage, identical coverage, daily caps, surcharge rules and data terms.
By Jordan Ellis · Editor
Published · Updated
Answer in brief
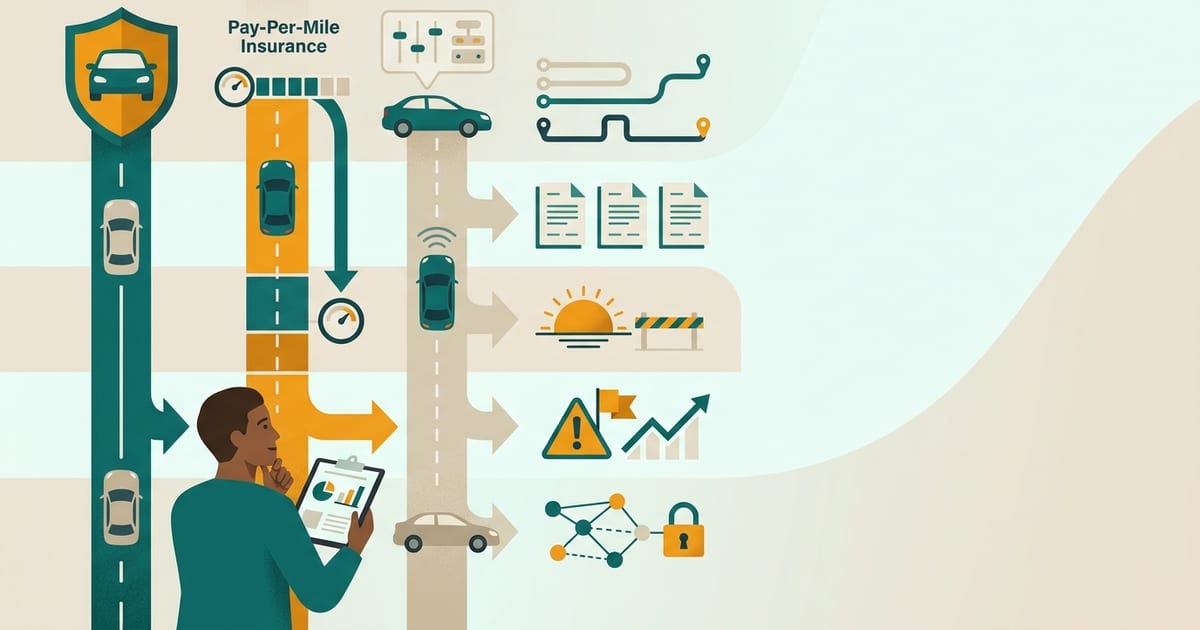
To compare pay-as-you-go quotes properly, start from your verified annual mileage and an identical coverage set, then convert each pay-per-mile quote to an annual figure (base × 12 + per-mile rate × miles) and set it beside conventional and telematics quotes for the same coverage. Check the daily mileage cap, whether the programme can raise rates, what data is collected and whether your vehicle and state are eligible. The cheapest option is often a conventional policy from a different insurer—so always include two or three in the comparison.
Step 1: Verify your mileage
Use odometer readings, not a guess. Pay-per-mile quotes are meaningless without a realistic number. See low-mileage drivers for the method.
Step 2: Fix the coverage
One set of liability limits, UM limits and deductibles for every quote. A pay-per-mile quote with lower limits is not cheaper—it is different.
Step 3: Annualise
Step 4: Check the terms
- Daily mileage cap and how out-of-state trips are handled.
- Whether the programme can increase your rate and under what conditions.
- Data collected and retention—see privacy and data.
- Device or app requirements and vehicle eligibility.
- Fees: device, installment, cancellation.
Step 5: Include conventional quotes
Two or three standard quotes from other insurers for the same coverage, with your accurate mileage declared. If one of them beats the usage-based options, take it; the goal is the lowest price for the coverage, not a particular product.
Quote finder
Find auto insurance quotes that fit your situation
Entries in this guide
Specific questions answered in more depth.
Questions & answers
How do I calculate a pay-per-mile premium?
Monthly base × 12, plus per-mile rate × annual miles.
Should I compare usage-based quotes with regular ones?
Yes. A conventional policy from a different insurer is sometimes cheaper even for low-mileage drivers.
Is pay-per-mile available everywhere?
No. Availability varies by state and insurer.
Terms used in this guide
- Per-mile rate
- The charge for each mile driven on a pay-per-mile policy, typically 3–12 cents, subject to a daily cap.
- Base rate (pay-per-mile)
- The fixed monthly portion of a pay-per-mile premium, covering risks that exist while the car is parked and the policy's fixed costs.
- Annual mileage
- Miles driven per year, a rating factor on every policy and the basis of pay-per-mile pricing. The national average is roughly 12,000–13,000.
Sources and references
Legal figures on this page (minimum limits, filing periods, statutory benefits) are checked against the primary law or the state insurance regulator listed below. Links and figures last verified Nov 2026.
- Background on: Pay-as-you-drive auto insurance (telematics) — Insurance Information InstituteIndependent researchUsage-based and per-mile pricing models, what telematics programmes measure, and state limits on their use.
- Nine ways to lower your auto insurance costs — Insurance Information InstituteConsumer guidanceShop at least three quotes; raising a deductible from $200 to $500 can cut collision/comprehensive cost 15–30%, $1,000 can save 40%+; drop physical damage on cars worth under 10× the premium; bundling, low-mileage and good-student discounts.
- Consumer insurance information — National Association of Insurance CommissionersConsumer guidancePlain-language guides from the body of state insurance regulators; links to every state's insurance department and complaint process.
- What determines the price of an auto insurance policy? — Insurance Information InstituteConsumer guidanceRating factors: driving record, mileage, location, age, gender, vehicle, credit-based insurance score, coverage choices. Notes ZIP-code rating is prohibited in California and Michigan and gender rating is prohibited in seven states.
- Car insurance — Consumer ReportsConsumer guidanceIndependent testing organisation's guides to comparing policies and insurers.
- Auto insurance basics — United PolicyholdersConsumer guidancePlain-language coverage explanations from a policyholder-advocacy non-profit.
Practical guidance on this page is original editorial work. Cited sources support factual statements and do not endorse this site. Dollar ranges described as typical or illustrative are editorial estimates, not figures from these sources.
Guide
Who Saves With Pay-As-You-Go Insurance
The driver profiles that benefit from pay-as-you-go pricing—remote workers, retirees, second cars, city dwellers, students—and the ones who should avoid it.
Guide
Pay-Per-Mile vs Telematics: Which Saves More?
A direct comparison of pay-per-mile and behaviour-based telematics—who each suits, how savings differ, and whether you can combine them.
Guide
Pros and Cons of Pay-As-You-Go Car Insurance
A balanced assessment of pay-per-mile and telematics policies: savings, flexibility and feedback against variable bills, privacy, device hassles and surcharge risk.