Entry in How to Compare Pay-As-You-Go Insurance Quotes
How to Calculate Your Break-Even Mileage for Pay-Per-Mile Car Insurance
Learn how to calculate your break-even mileage to determine if pay-per-mile car insurance will save you money compared to a standard fixed-rate policy.
By Jordan Ellis · Editor
Published
Answer in brief
To calculate your break-even mileage for pay-per-mile car insurance, subtract your quoted annual base rate from your current standard premium and divide the remainder by your per-mile rate. Driving fewer miles than this calculated threshold means a pay-per-mile policy saves you money, while exceeding it indicates a traditional flat-rate policy is more economical.
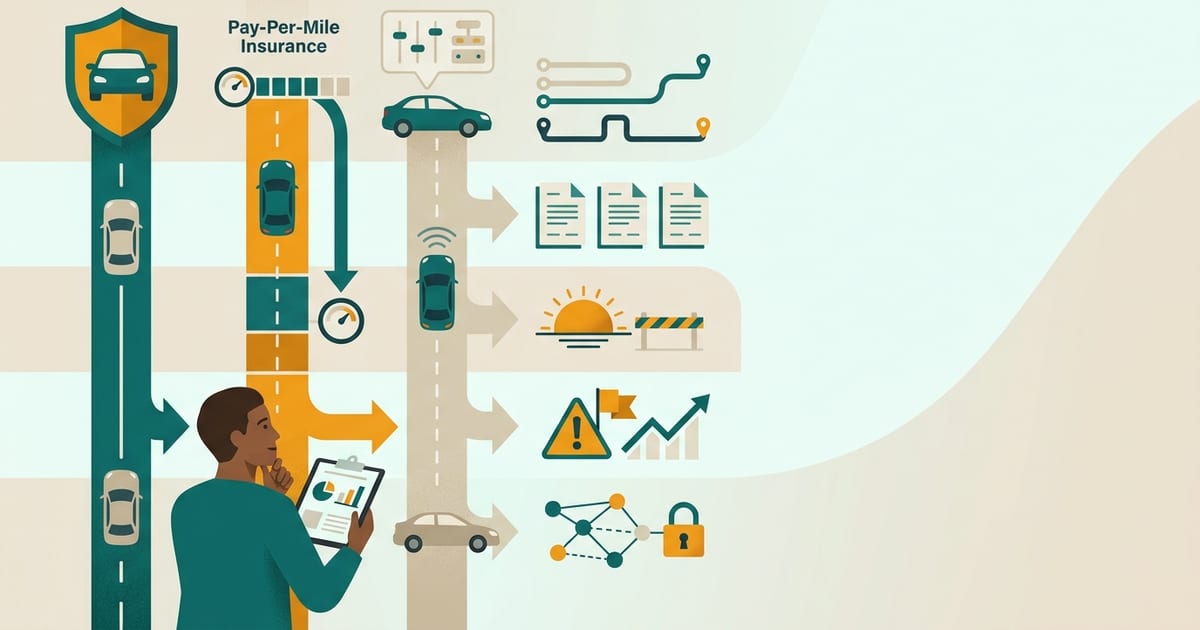
For households that drive significantly less than national averages, switching to pay per mile car insurance can produce meaningful annual savings. Traditional automobile policies charge a static premium regardless of whether a vehicle travels 3,000 miles or 13,000 miles in a calendar year. Pay-as-you-go pricing restructures this expense into two distinct segments: a fixed monthly base rate that maintains comprehensive, collision, and liability protections while parked, paired with a variable per-mile rate charged only when the wheels turn.
However, pay-as-you-go models do not guarantee lower bills for every driver. The key to evaluating a policy is identifying your exact break-even mileage—the precise odometer count where the combined base and per-mile charges equal the cost of an equivalent flat-rate premium. Understanding how to calculate this figure lets you determine whether your routine driving volume makes usage-based pricing beneficial before you alter your coverage.
The Pay-Per-Mile Break-Even Formula Explained
Calculating your break-even threshold requires three data points: your annual premium under a traditional policy, your prospective annual base rate under a pay-per-mile plan, and the prospective per-mile rate. Because traditional insurance premiums reflect factors such as your driving record, vehicle model, geographic location, and coverage selections, you should always compare policies that feature identical liability limits and physical damage deductibles.
To ground this formula in realistic national context, the National Association of Insurance Commissioners reported a countrywide average insurance expenditure of $1,281 in 2023. If a driver pays an illustrative annual flat premium of $1,400 and receives a pay-as-you-go quote consisting of a $45 monthly base rate ($540 annually) plus $0.08 per mile, the equation is straightforward: ($1,400 − $540) ÷ $0.08 = 10,750 miles. In this scenario, driving fewer than 10,750 miles per year produces savings.
- 1
Gather Your Standard Coverage Baseline
Obtain your current policy declarations page to note your total annual premium, bodily injury liability, property damage liability, and collision and comprehensive deductibles. Having identical coverage levels is essential for an accurate mathematical comparison.
- 2
Calculate Your Total Annual Base Rate
Review your pay-per-mile quote to find the monthly base charge. Multiply that monthly figure by 12 to establish your baseline annual holding cost, which covers your vehicle against non-driving perils such as theft, vandalism, and weather damage.
- 3
Identify the Exact Per-Mile Charge
Note the quoted variable rate per mile, which typically ranges from several cents to around ten cents depending on individual risk factors such as age, vehicle type, and driving safety record.
- 4
Execute the Division to Find Your Annual Ceiling
Subtract your annual base rate from your traditional annual premium. Divide that remaining dollar balance by the per-mile rate to reveal your maximum break-even odometer reading for the year.
Break-Even Mileage Scenarios Across Different Driving Habits
Because base and per-mile rates vary by driver risk profile, the break-even threshold shifts depending on individual quotes. Below is an illustrative breakdown showing how different rate structures interact with various driving volumes compared to an illustrative traditional annual premium of $1,350.
| Monthly Base Rate | Annual Base Cost | Per-Mile Rate | Break-Even Mileage | Cost at 5,000 Miles | Annual Savings at 5,000 Miles |
|---|---|---|---|---|---|
| $35 | $420 | $0.06 | 15,500 miles | $720 | $630 |
| $45 | $540 | $0.08 | 10,125 miles | $940 | $410 |
| $55 | $660 | $0.09 | 7,667 miles | $1,110 | $240 |
| $65 | $780 | $0.11 | 5,182 miles | $1,330 | $20 |
As demonstrated in the comparison table, drivers logging under 6,000 annual miles generally capture substantial savings under most pay-per-mile rate configurations. However, if your base rate or per-mile surcharge is elevated due to past violations or higher vehicle repair costs, your break-even point contracts, requiring a lower driving volume to justify the structure over a traditional policy.
Factoring Deductibles and Statutory Rules into the Math
Adjusting physical damage deductibles can dramatically reshape both traditional and pay-as-you-go pricing. According to the Insurance Information Institute, increasing a collision or comprehensive deductible from $200 to $500 can reduce coverage costs by 15% to 30%, while opting for a $1,000 deductible can cut physical damage premiums by 40% or more. Lowering your baseline policy cost through higher deductibles will lower your break-even threshold, meaning your pay-per-mile rate must remain competitive to maintain financial advantage.
State legal frameworks also dictate how mileage impacts pricing. In California, under California Insurance Code § 1861.02, insurance rates must be determined primarily by three factors in decreasing order of importance: driving safety record, annual miles driven, and years of driving experience. This statutory weighting gives mileage substantial influence even on conventional policies. Conversely, the Texas Department of Insurance notes that no state law requires auto insurers to offer specific low-mileage discounts, making direct pay-per-mile tracking one of the few guaranteed methods for Texas drivers to tie premiums directly to reduced vehicle use.
Drivers should also account for long road trips. Many pay-as-you-go insurers incorporate daily mileage caps, typically charging for no more than 250 miles in a single 24-hour window. As explored in our guide on daily mileage caps explained, these caps prevent occasional vacations or cross-country drives from skewing your annual break-even economics.
Questions & answers
What is break-even mileage in car insurance?
Break-even mileage is the specific annual distance at which the total cost of a pay-per-mile policy (base rate plus mileage charges) exactly matches the premium of a traditional fixed-rate policy.
How do daily mileage caps affect my break-even calculation?
Daily caps stop billing after a set daily mileage limit (often 250 miles per day). If you take periodic road trips, your billed miles will be lower than your actual odometer increase, raising your practical break-even threshold.
Can changing my deductible change my break-even point?
Yes. Raising your collision and comprehensive deductibles lowers the total premium for both traditional and pay-per-mile policies. Because physical damage savings reduce the overall premium spread, your calculated break-even mileage will adjust accordingly.
Does my base rate stay the same every month?
Yes, under standard pay-per-mile agreements, your monthly base rate remains constant throughout your six-month or annual policy term, altering only at renewal based on standard underwriting review.
Terms: Base rate (pay-per-mile), Per-mile rate, Annual mileage, Pay-per-mile insurance, Low-mileage discount
Sources and references
Legal figures on this page (minimum limits, filing periods, statutory benefits) are checked against the primary law or the state insurance regulator listed below. Links and figures last verified Nov 2026.
- Insurance Code § 1861.02 — rating factors and Good Driver Discount — California Legislative Information, Cal. Ins. Code § 1861.02Primary lawRates must be determined by, in decreasing order of importance, driving safety record, annual miles driven and years of driving experience; optional factors may follow. Good Driver Discount policies must be at least 20% below the rate otherwise charged.
- Companies may offer auto insurance discounts. No law requires discounts. — Texas Department of Insurance (2025)State insurance regulatorNo Texas law or rule mandates auto insurance discounts (for age, low mileage or anything else) or puts a time limit on them; advertising that says otherwise is misleading.
- Background on: Pay-as-you-drive auto insurance (telematics) — Insurance Information InstituteIndependent researchUsage-based and per-mile pricing models, what telematics programmes measure, and state limits on their use.
- 2019–2023 Auto Insurance Database: average premium supplement — National Association of Insurance Commissioners (2025)Statistical dataCountrywide average expenditure $1,281 in 2023 (+13.98%); combined average premium $1,438; state tables for liability, collision and comprehensive.
- Nine ways to lower your auto insurance costs — Insurance Information InstituteConsumer guidanceShop at least three quotes; raising a deductible from $200 to $500 can cut collision/comprehensive cost 15–30%, $1,000 can save 40%+; drop physical damage on cars worth under 10× the premium; bundling, low-mileage and good-student discounts.
- What determines the price of an auto insurance policy? — Insurance Information InstituteConsumer guidanceRating factors: driving record, mileage, location, age, gender, vehicle, credit-based insurance score, coverage choices. Notes ZIP-code rating is prohibited in California and Michigan and gender rating is prohibited in seven states.
Practical guidance on this page is original editorial work. Cited sources support factual statements and do not endorse this site. Dollar ranges described as typical or illustrative are editorial estimates, not figures from these sources.