Entry in Pros and Cons of Pay-As-You-Go Car Insurance
Telematics and Pay-Per-Mile Car Insurance for Young Drivers: Pros and Cons
Discover the pros and cons of telematics and pay-per-mile car insurance for young and teen drivers. Learn how driving scores and mileage impact premiums.
By Hana Sato · Writer
Published
Answer in brief
Telematics and pay-as-you-go car insurance offer young motorists a data-driven way to offset high baseline premiums by proving safe driving habits or logging limited miles. Because insurers heavily weigh statistical age and lack of driving experience, usage-based programs allow careful young drivers to earn meaningful rate discounts. However, strict nighttime curfews, mobile phone detection, and high base fees present important trade-offs to evaluate before enrolling.
Insuring a young driver is often one of the most expensive line items in a household budget. Traditional auto insurance models rely heavily on broad demographic actuarial tables, which place teenage and early-twenties motorists into the highest-risk pricing brackets regardless of their personal caution behind the wheel.
For families facing steep rate hikes, telematics and pay-per-mile car insurance present an alternative: replacing demographic assumptions with real driving data. By tracking mileage or monitoring road behaviors through smartphone apps and plug-in devices, these programs provide a pathway to lower rates for disciplined, low-mileage young drivers.
The Actuarial Reality Behind High Young Driver Rates
To understand why telematics is popular among young drivers, one must examine the baseline crash statistics that drive traditional insurance pricing. Actuarial data shows that inexperience creates severe exposure on the road.
Data compiled by the Insurance Institute for Highway Safety (IIHS) reveals that the fatal crash rate per mile driven for 16-to-19-year-olds is just over three times higher than the rate for drivers aged 20 and older, with crash risk peaking at ages 16 and 17. Furthermore, Insurance Information Institute records show drivers aged 16 to 20 had 42.40 fatal-crash involvements per 100,000 licensed drivers in 2023, while drivers aged 21 to 24 recorded 35.34.
Because standard rating formulas factor in age and driving experience—such as in California where Cal. Ins. Code § 1861.02 mandates driving safety record, annual mileage, and years of driving experience as the primary rating determinants—young motorists face heavy premiums unless they can empirically demonstrate lower risk.
Telematics vs. Pay-Per-Mile: Which Model Fits Young Drivers?
Usage-based programs fall into two primary structures, each answering a different driving reality:
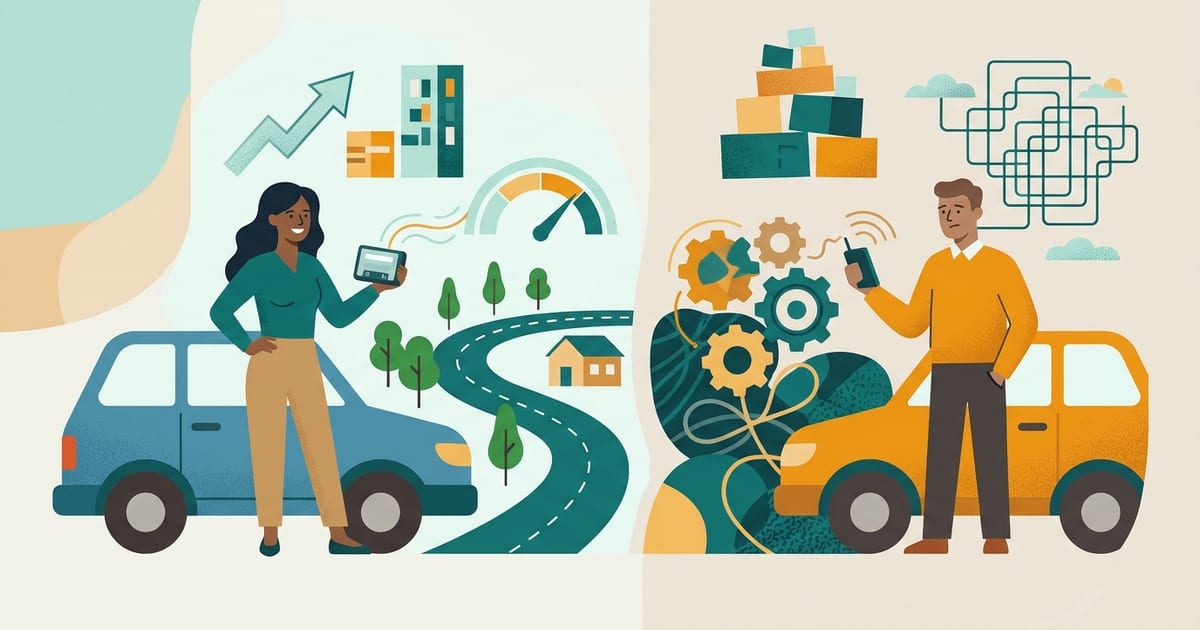
- Behavioral Telematics: Measures how you drive. An app or plug-in device monitors acceleration, braking intensity, cornering, vehicle speed, phone movement while moving, and time of day to produce a cumulative driving score. Safer scores translate to policy discounts upon renewal.
- Pure Pay-Per-Mile: Measures how much you drive. Insurers charge a predictable monthly base rate plus a fixed per-mile rate. How aggressively the car is driven is not factored into the per-mile fee, making it ideal for young adults who leave their car parked on college campuses or walk to school.
Weighing the Pros and Cons for Young Drivers
Enrolling in a tracking program involves balancing measurable financial savings against behavioral constraints and monitoring. Review the primary trade-offs before activating a policy.
| Factor | Pros (Advantages) | Cons (Trade-offs) |
|---|---|---|
| Premium Control | Enables safe young drivers to decouple from broad demographic surcharges and earn discounts. | Poor driving scores or excessive mileage can eliminate anticipated discounts, leaving premiums high. |
| Driving Habits | Real-time feedback apps encourage smoother braking, less phone handling, and safer speeds. | Sudden defensive braking to avoid road hazards can still register as a negative hard-braking event. |
| Low Mileage Fit | College students living on campus without a commute pay only for infrequent weekend trips. | Young drivers with long daily school or work commutes can quickly exceed the mileage break-even mark. |
| Discount Stacking | Can be paired with traditional discounts such as good student and defensive driving credits. | Some carriers charge higher base rates for inexperienced drivers, blunting the net savings. |
Checklist Before Enrolling a Young Driver in a Tracking Program
To ensure that telematics or pay-as-you-go coverage lowers your household expenses, complete these evaluation steps before enrolling.
- 1
Analyze Schedule and Curfews
Examine the young driver's typical weekly schedule. If employment or school activities require regular travel during late-night hours (typically 12:00 AM to 4:00 AM), avoid behavioral telematics programs that heavily penalize late-night operation.
- 2
Establish Phone Handling Protocols
Many smartphone-based telematics apps monitor screen interaction while the vehicle is in motion. Make sure the young driver understands that touching the phone to change music or check messages while driving directly suppresses their driving score.
- 3
Stack Traditional Savings First
Ensure the carrier also applies conventional credits noted by the Insurance Information Institute, including good-student discounts (typically requiring a B average or better) and higher physical damage deductibles to optimize total costs.
- 4
Review Rate Increase Disclosures
Read the insurer's policy terms regarding score outcomes. While many carriers use telematics strictly to grant discounts, some programs reserve the right to increase rates on drivers who log poor driving scores or frequent high-speed events.
Questions & answers
Can a bad driving score raise a young driver's car insurance rate?
It depends on the insurer's specific telematics program terms and state regulations. Some carriers guarantee that telematics data will only be used to apply a discount, meaning a poor driving score simply results in zero savings. However, other carriers filed rating plans that allow them to surcharge premiums if the device records severe speeding, hard braking, or extensive late-night driving. Always verify whether a program includes rate-increase exposure before enrolling.
Is pay-per-mile or behavioral telematics better for a college student?
Pay-per-mile is often superior for college students who leave their car parked on campus most of the week, as they only pay a low monthly base rate plus cents per mile when running occasional errands. Behavioral telematics is generally better suited for young drivers who commute daily but practice exceptionally cautious driving habits without late-night travel.
Can young drivers combine telematics discounts with good-student discounts?
Yes. Most insurers permit policyholders to stack usage-based telematics savings with traditional rating discounts, including good-student discounts for maintaining a 3.0 GPA, driver training credits, and multi-car family discounts.
What happens if a young driver is a passenger in a friend's car while using a mobile telematics app?
Smartphone-based telematics apps use algorithms to differentiate drivers from passengers, but misidentifications occur. Most carrier apps allow the user to review logged trips within a set window (often 14 to 30 days) and reclassify a trip from 'driver' to 'passenger' or 'public transit' so that a friend's driving does not affect the young driver's score.
Terms: Driving score, Telematics (usage-based insurance), Pay-per-mile insurance, Base rate (pay-per-mile), Per-mile rate
Sources and references
Legal figures on this page (minimum limits, filing periods, statutory benefits) are checked against the primary law or the state insurance regulator listed below. Links and figures last verified Nov 2026.
- Insurance Code § 1861.02 — rating factors and Good Driver Discount — California Legislative Information, Cal. Ins. Code § 1861.02Primary lawRates must be determined by, in decreasing order of importance, driving safety record, annual miles driven and years of driving experience; optional factors may follow. Good Driver Discount policies must be at least 20% below the rate otherwise charged.
- Background on: Pay-as-you-drive auto insurance (telematics) — Insurance Information InstituteIndependent researchUsage-based and per-mile pricing models, what telematics programmes measure, and state limits on their use.
- Teenagers — Insurance Institute for Highway SafetyIndependent researchTeen crash risk, graduated driver licensing research and vehicle recommendations for young drivers.
- Graduated licensing laws by state — Insurance Institute for Highway SafetyIndependent researchState-by-state learner, intermediate and full-licence ages, night-driving and passenger restrictions.
- Fatality facts: Teenagers — Insurance Institute for Highway Safety (2024)Statistical dataFatal crash rate per mile driven for 16–19-year-olds is just over 3 times the rate for drivers 20 and older (2022 travel data); all-severity crash rate is over 4 times; risk is highest at 16–17.
- Drivers in fatal motor vehicle crashes by age, 2023 — Insurance Information Institute (2025)Statistical dataFatal-crash involvement per 100,000 licensed drivers: 42.40 (16–20), 35.34 (21–24), 28.97 (25–34), 24.18 (35–44), 21.70 (45–54), 19.45 (55–64), 15.44 (65–74), 16.63 (75+).
- What determines the price of an auto insurance policy? — Insurance Information InstituteConsumer guidanceRating factors: driving record, mileage, location, age, gender, vehicle, credit-based insurance score, coverage choices. Notes ZIP-code rating is prohibited in California and Michigan and gender rating is prohibited in seven states.
- Nine ways to lower your auto insurance costs — Insurance Information InstituteConsumer guidanceShop at least three quotes; raising a deductible from $200 to $500 can cut collision/comprehensive cost 15–30%, $1,000 can save 40%+; drop physical damage on cars worth under 10× the premium; bundling, low-mileage and good-student discounts.
Practical guidance on this page is original editorial work. Cited sources support factual statements and do not endorse this site. Dollar ranges described as typical or illustrative are editorial estimates, not figures from these sources.